Window opens as France stabilises, letting pragmatic trio through as selectivity rises
A stabilisation in the OAT-Bund spread and decoupling of credit from the French rollercoaster allowed for the successful launch of three euro benchmark covered bonds this week, with issuers prioritising certainty in execution over the best possible window. Further FIG supply will remain subject to headline risk and investor caution, but could prove timely. Neil Day reports, with insights from Crédit Agricole CIB.
You can download a pdf of this BIHC Briefing here.
The market ended the week on a stabler footing than might have been imagined last weekend, albeit with bumps along the way. And with volatility moderating, levels for investors and issuers, as well as technicals, could provide a constructive backdrop for supply.
Central to the improvement was an easing of fears around France — for now, at least. Having traded as high as 92 on Friday of last week (2 October), France CDS had recovered to 77 by this Friday, with the 10 year OAT-Bund spread closing the week shy of 140bp, around 20bp inside last Friday’s intraday peak of 159bp.
“The rhetoric has changed quite dramatically,” said William Rabicano, director, credit trading at Crédit Agricole CIB. “Two weeks ago, with the 10 year OAT-Bund spread at 120bp and people speculating about 150bp, there were some gasps and disbelief that we might go there, but when we reached the mid to high 140s all of a sudden last Friday, 175bp and even 200bp didn’t sound so crazy.
“But the conversations I’ve been hearing around France now are that people are a lot more comfortable with where valuations are. They feel like a lot of the bad news is now priced in, and it definitely feels like people are much more comfortable holding risk at these levels than they were a week or so ago. And we’ve definitely seen France start to outperform in the last couple of sessions.”
And while credit had been dragged wider by the moves in European government bond markets, this pressure, too, eased through the week.
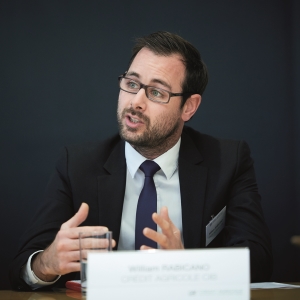
“It does feel like our beta to other asset classes is shrinking a little,” said Rabicano (pictured). “Last Friday, when OATs were 10bp wider, credit spreads were equally 10bp wider. But at the start of this week, when OATs moved 10bp wider, credit was 2bp, 3bp or 4bp wider. That should be positive for credit, because it gives people a little bit more confidence that the volatility is subsiding.
“Clients are being selective,” he added. “They don’t want to chase risk on a strong day. They’re much more inclined to wait for the dust to settle before making a call one way or the other.”
“Liquidity is thin and conviction is low.”
Indeed, a recovery in the first two days of the week was snuffed out on Wednesday, but not before three issuers took advantage of the better tone to launch secured issues. On Tuesday, ABN Amro and Mediobanca launched the first euro FIG benchmarks of the week, three year covered bonds that proved successful.
“We had been monitoring the market for one or two sessions, wondering whether it could make sense,” said André Bonnal, FIG syndicate at Crédit Agricole CIB, joint bookrunner on both trades, “and after a stable day on Monday, Tuesday opened positively, and ended up having an even stronger tone than we had expected.”
The Dutch bank led the way, attracting more than €2bn of orders, excluding joint lead manager interest, to its euro benchmark, enabling a size of €1.5bn and pricing of 14bp over mid-swaps, 4bp inside guidance of the 18bp area.
“ABN Amro was the right name to test the water,” said Vincent Hoarau, head of FIG syndicate at Crédit Agricole CIB. “A core jurisdiction with an outperforming government curve, a well-established issuer and a solid investor base. When you reopen a market, you don’t want the first trade to be open to debate.”
Mediobanca hit screens shortly after ABN Amro and upsized its trade from an expected €500m to €750m on the back of a peak €1.2bn-plus book, with pricing tightened from the 35bp area to 30bp, and a final book above €1bn, excluding JLMs.
Syndicate bankers at and away from the leads were positive about the execution of both trades, which, if anything, went even better than anticipated. Lead bankers highlighted the quality of the order books, lacking fast money following the recent shake-out.
“Success has been redefined, in terms of book composition and granularity, rather than multiples of oversubscription,” added Hoarau.
The new issue premiums for the two trades were up to 5bp.
“Supply has been well absorbed, but priced with more care,” said Hoarau. “There was no panic-selling, even in the worst sessions, but this was not just a remarking exercise. We saw real selling flows in both covered and unsecured.
“In covered, accounts that sold blocks in secondary last week were buyers in primary at wider levels, capturing the extra spread and the new issue premium. In senior and sub, we suspect investors were also selling to make room for more attractive primary deals. Overall, accounts remain net sellers and cash balances are building.”
Although conditions were deteriorating the next day, Canada’s Equitable Bank, which had announced a mandate the previous Wednesday (30 September), launched a €500m no-grow December 2029 trade. Pricing was tightened from the 38bp area to 34bp on the back of orders above €1bn, with the final book reaching more than €1.2bn, including €125m of JLM interest.
The pricing was deemed pragmatic — key for anyone considering the market today, according to Hoarau (pictured).
“We have come to a point where issuers mandate not to capture the best window,” he said, “but to print an ‘okay’ trade when a window opens. They know things could deteriorate further. The priority is execution certainty.”
Unsecured European bank issuance did not dry up completely — Deutsche Bank on Wednesday turned to the sterling market with a £500m (€590m) short six year non-call five green senior non-preferred issue. After attracting peak demand above £1.65bn, pricing was tightened some 20bp to Gilts plus 115bp, or 131bp over mid-swaps, for a new issue premium of 7bp-8bp. This put it some 5bp inside what a comparable euro issue for the German bank might have achieved, although in tandem with this the book fell by around a third to some £1.07bn.
The sterling trade was a quick follow-up by Deutsche to a $1bn (€892m) four non-call three senior non-preferred issue on Tuesday.
Ultimately, the week ended on a constructive note after some consolidation on Thursday, with equities up on Friday, rates down, oil lower, and OATs recovering modestly against Bunds.
“It’s good to finish the week on a bit more of a positive note after the past couple of days, which were more difficult,” said Bonnal. “Wednesday was particularly damaging for investors’ mindset, completely erasing Tuesday’s gains when they might have hoped for stability.
“I think the market is starting to learn to live with the overall volatility, but it’s naturally helpful to have the OAT-Bund spread moving within plus or minus 3bp rather than 10bp!”
Meanwhile, the market setbacks have left the entry point for investors looking potentially more interesting.
“In terms of i-spreads, and how they look versus two or three weeks ago, some value has returned for investors,” said Bonnal. “And since we’ve had Bunds outperforming swaps, the overall spread complex versus Bunds is even better.”
Senior preferred bonds ended the week on average 3bp-5bp wider than in the week commencing 21 September, with senior non-preferred some 5bp-8bp wider, and Tier 2 around 10bp wider. French credits underperformed significantly.
“I’m not saying that there’s a massive scope for performance,” he added, “but investors may feel they are being a little more compensated for risk versus, say, mid-August, when everything was super-tight. So we could see credit being relatively well supported in terms of overall tone and bid in the next couple of weeks.”
As well as the wider levels, technicals could prove supportive, according to Bonnal. This week’s limited euro FIG issuance came after similarly scant supply the preceding week, when La Banque Postale provided the only unsecured supply, a €750m four non-call three senior non-preferred deal, and only one benchmark covered bond emerged, a €500m seven year green Spuerkeess (BCEE) debut.
“I don’t expect much in the coming week,” he said. “Most issuers are entering blackout periods, so we’re naturally heading into the typical quiet period in the second half of October. But don’t confuse quiet with lack of appetite. Banks have largely completed their 2026 funding plans, yet many want to get a headstart on 2027, and anyone outside blackout will look at the market if the tone allows.
“Combine that with having had very limited supply in the past two weeks, and the lack of supply may start feeding into a more constructive secondary market in the meantime. The question will then be, how much pre-funding do we see in the November calendar?”
And while spreads — notably to Bunds — have become more tempting for investors, issuers — looking on an i-spread basis — will still see levels that are relatively attractive versus where they have been over the course of the year, noted Bonnal (pictured).
“On an i-spread basis, we are still within touching distance of where things were getting done in, say, mid-September,” he added. “Once results are out of the way, we may even see too many issuers rushing in at the same time, particularly after the US mid-terms.”
Hoarau, however, cautioned that the constructive technical backdrop rests on fragile foundations.
“A backlog is building. Many issuers are waiting for stability before pulling the trigger on 2027 pre-funding, and corporates have their own pipeline to clear. If the macro backdrop stays fragile, that backlog means pressure on pricing parameters, not relief.
“We need a strong positive catalyst to offset the challenge France poses to primary execution and spread stability. And part of the value investors see today could evaporate: if Bunds cheapen back against swaps, the pick-up over Bunds that makes FIG look attractive goes with it.
“More and more accounts fear outflows, so they will be more disciplined on cash balances,” added Hoarau. “Even at attractive levels, their inclination to deploy in full will be limited. Meanwhile, equities look fragile even at new highs. It’s all about AI promises, and any disappointment could derail recovery attempts.”
The upside scenario is meanwhile relatively straightforward.
“A resolution in the Strait of Hormuz and relief on oil prices would feed through into inflation and the ECB narrative, and that is the catalyst this market needs,” said Hoarau. “Without it, the run into year-end could prove challenging, and January more measured than the usual rush.
“Issuers would therefore be well advised to take every opportunity that presents itself. All else being equal, spreads remain very competitive on a historical basis, particularly versus Bunds, while re-offer yields are very attractive for investors.”